- Locations
- San Antonio
- Roof Insurance Claims Assistance
Roof Insurance Claim Help in San Antonio, TX – Hail & Storm Damage Claims
Summary
Apex Roofing & General Contractors helps San Antonio homeowners and businesses through roof insurance claims after hail and wind damage: a free 37-point inspection, dated photo and drone documentation, an on-site adjuster meeting, scope review, and supplement requests – then the approved repair or replacement. We document the roof and do the work; under Texas law the claim decisions stay yours. Most Texas policies carry a 1% or 2% wind/hail deductible; Texas insurers must acknowledge a claim within 15 days and decide within 15 business days of receiving your documentation.
Key Takeaways
- Roof insurance claim help in San Antonio, TX for homeowners and businesses, from the W Hausman Rd office, across Bexar County.
- Documentation is what wins claims: dated photos of every slope, drone imaging, test-square hail counts, and a written scope that separates storm damage from wear.
- Coverage hinges on Actual Cash Value (ACV) vs Replacement Cost Value (RCV) – on a 15-plus-year roof the difference can be half the payout.
- Report damage promptly: most Texas policies set a notice window (often one year for weather claims) – check yours; the Texas Insurance Code sets the insurer’s clock at 15 days to acknowledge, 15 business days to decide, 5 business days to pay.
- Common denial reasons: damage classified as wear and tear, missing documentation, late notice, and storm-chaser paperwork signed at the door.
- A Texas contractor cannot negotiate your settlement, act as your adjuster, or waive your deductible; Apex documents, meets the adjuster, and builds the supplement – the decisions are yours, and claim help is included at no extra cost when we do the work.
- Not sure it’s worth filing? The Hail Damage Claim Checker compares the likely repair cost to your deductible in 30 seconds.


Roof Insurance Claims Assistance

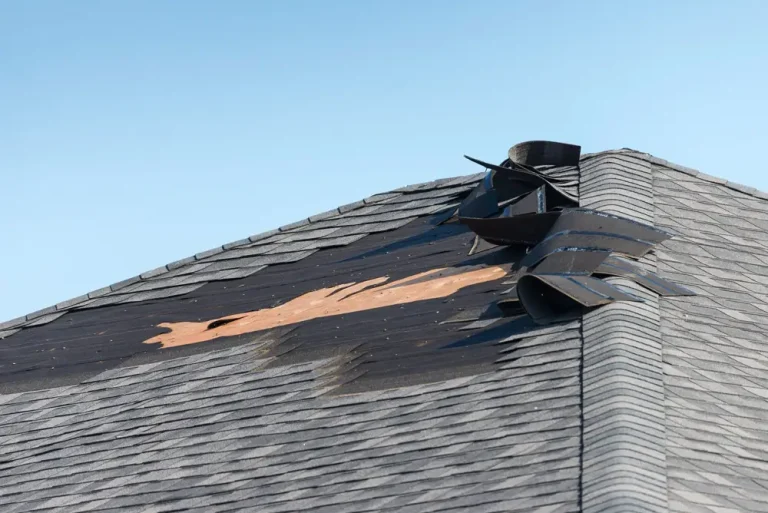
Yes, Apex Roofing & General Contractors helps San Antonio homeowners with roof insurance claims – and the help starts before you file, with a free 37-point inspection that tells you whether a claim is worth making. Filing on your own often means facing an adjuster with far more experience reading roof damage than the average homeowner has, and that gap can mean the difference between a fair settlement and a denied or underpaid claim. Apex Roofing & General Contractors works alongside homeowners and businesses through the entire San Antonio roof insurance claims process, from the first inspection to the final approved scope of work, so your claim reflects the actual extent of the damage instead of a rushed estimate.
As a licensed San Antonio roofing contractor, we know what adjusters look for and how storm damage is underestimated without a trained eye. Our free roof inspection documents every detail with dated photos, drone imaging, and a written report, and we meet your adjuster on site whenever possible so nothing gets overlooked before your claim is finalized. We work with claims from every major carrier in the area, including USAA – headquartered here in San Antonio – State Farm, Allstate, Farmers, and Texas Farm Bureau. Call (726) 727-7663 or book the inspection online.
Book Your Free 37-Point Storm Inspection Before You File
Hail Damage Roof Insurance Claims in San Antonio: Why Documentation Decides the Outcome
San Antonio’s hail and wind events regularly generate a surge of claims across the same neighborhoods in a short window, whether it’s a residential rooftop or a commercial low-slope system, which means adjusters are often moving quickly through inspections and may miss damage that a roofing specialist would catch. Texas insurance policies also vary widely in how they define recoverable depreciation, code upgrade coverage, and matching requirements for shingles or roofing materials that are no longer manufactured. Commercial and multi-family properties add another layer of complexity, since larger roof surfaces and specialized membrane systems make thorough documentation even more important to avoid an underpaid claim. The National Weather Service Austin/San Antonio office issues Bexar County’s hail and severe-thunderstorm warnings and posts storm reports after each event; the date and hail size in those reports are the first thing an adjuster checks against your claim, so note the storm date before you call.
Without someone who reads roofs for a living present during the adjuster visit, it’s common for property owners to accept an estimate that only covers part of the actual repair. According to the Texas Department of Insurance, homeowners have the right to request a reinspection or file a complaint if they believe a claim was underpaid, and understanding that process is part of what Apex Roofing & General Contractors walks clients through, for residential and commercial properties alike.
Common Reasons San Antonio Roof Insurance Claims Get Denied or Underpaid
Most denied or underpaid claims come down to a small set of recurring issues, and knowing them ahead of time makes it easier to avoid the same mistakes. The table below shows what we see most often on San Antonio claims and how Apex Roofing & General Contractors works to resolve each one.
Reason for Denial or Underpayment | What It Means | How Apex Roofing & General Contractors Helps |
Damage classified as wear and tear | Adjuster attributes hail or wind marks to aging materials instead of a specific storm | We provide dated storm data and side by side photos tied to the actual event |
Missing or incomplete photo documentation | Claim was filed without enough visual evidence to support the reported damage | We document every slope with time stamped photos and video before the claim is filed |
Partial approval for visible damage only | Adjuster approves the obvious spots but misses less visible issues like flashing or decking | We point out easily missed damage areas during the adjuster walkthrough |
Matching shingle disputes | Insurer proposes a patch repair using discontinued or mismatched shingles | We document matching requirements and cite discontinued products to support full slope or full roof coverage |
Missed filing deadline | Homeowner reports the damage after the policy’s reporting window has passed | We encourage a prompt post storm inspection so damage is documented well within the filing window |
If any of these reasons sound familiar from a past or current claim, it is worth having Apex Roofing & General Contractors take a second look before you accept the outcome. The National Association of Insurance Commissioners notes that policyholders have the right to appeal a denied or underpaid claim, and understanding your policy’s specific language is often the first step toward a stronger appeal.
Storm-chaser paperwork. After every San Antonio hailstorm, out-of-town crews knock doors with a “free inspection” and a form to sign. That form is often an assignment of benefits or a contingency agreement that commits you to that company before an adjuster has seen the roof, and it is one of the most common reasons a claim stalls. No legitimate roofer needs a signature to inspect a roof. Get the free inspection and the written report first; sign nothing at the door.
Signs You Need Roof Insurance Claims Assistance in San Antonio
Not every roof claim goes smoothly, and some situations call for extra support to make sure you’re not shortchanged. Here are the key signs it’s time to bring in professional help.
- Your adjuster’s estimate seems low compared to the visible damage on your roof after a hailstorm or windstorm.
- Your claim was denied outright, even though neighboring homes on your street received approved claims from the same storm.
- The estimate only covers a partial repair instead of the full replacement your roof actually needs.
- You are unsure what your policy covers, including recoverable depreciation, code upgrades, or matching shingle requirements.
- You have not had a professional roof inspection since the storm and are filing based on a visual check from the ground.
- Your insurance company is requesting a reinspection and you want a roofing professional present to advocate for the claim.
What Homeowners Insurance Typically Covers for Roof Storm Damage in San Antonio
Coverage can vary quite a bit between policies, and knowing what is usually included helps set realistic expectations before you file for storm damage roof repair in San Antonio. The table below outlines what most standard Texas homeowners policies cover for storm related roof damage and where extra documentation tends to make the difference.
Coverage Item | Typically Covered | Often Requires Documentation or Negotiation |
Wind and hail damage to shingles | Yes, under most standard homeowners policies | Extent of damage and confirmation of the storm date |
Full roof replacement due to storm damage | Yes, when damage exceeds what a repair can reasonably fix | Adjuster agreement that repair alone is not sufficient |
Recoverable depreciation | Yes, paid after the work is completed and documented | Submission of the final invoice and completion photos |
Code required upgrades | Varies by policy, some require an added endorsement | Confirmation of current local building code requirements |
Matching shingles across an aged roof | Varies, some insurers argue a partial match is acceptable | Proof that the original shingles are discontinued and cannot be matched |
Interior damage from a roof leak | Yes, typically covered as resulting water damage | Documentation linking the leak directly to the storm event |
Since every policy reads a little differently, our team reviews your specific coverage during the free inspection so there are no surprises once the claim is filed.
ACV vs. RCV: How Your Roof’s Age Affects Your Payout
How your insurance policy calculates your payout can significantly affect what you actually receive for a roof claim, and it largely depends on whether your policy uses Actual Cash Value (ACV) or Replacement Cost Value (RCV).
- Actual Cash Value (ACV) accounts for depreciation based on your roof’s age and condition at the time of the claim. This means an older roof will receive a lower payout than a newer one, even for the same type and extent of damage, since the insurer factors in the roof’s remaining useful life.
- Replacement Cost Value (RCV) covers the full cost to repair or replace your roof with similar materials, without deducting for depreciation. Many RCV policies still withhold the depreciated amount upfront and release it as “recoverable depreciation” once the repair or replacement is completed and documented.
Understanding which type of policy you have matters, because it affects both your upfront payout and what you may be entitled to recover later. If your roof is older, an ACV policy can mean a meaningfully smaller settlement than you might expect. Our team can help you understand how your policy type applies to your specific claim, and what documentation is needed to recover any depreciation you may be owed.
Your Rights and Deadlines as a San Antonio Homeowner
Report storm damage as soon as you find it. Most Texas homeowner policies require prompt notice and many set a one-year window for weather-related claims, so check the notice condition in your own policy. The law sets the insurer’s deadlines, not yours: under the Texas Insurance Code, Chapter 542, the carrier must acknowledge your claim within 15 days, accept or reject it within 15 business days of receiving everything it asked for, and pay within 5 business days of accepting it. If you later have to sue, Chapter 542A requires 60 days’ written notice first.
You have the right to a written explanation if your claim is denied, to request a reinspection if you disagree with the adjuster’s findings, and to file a complaint with the Texas Department of Insurance if your claim was mishandled or underpaid. Apex Roofing & General Contractors documents your damage thoroughly and supports you through the process, but the decision to accept, dispute, or appeal a settlement always remains yours.
What a Roofing Contractor Can and Cannot Do During Your Insurance Claim
It’s important to understand the legal boundaries of what a roofing contractor can help with during your insurance claim, since this protects you from arrangements that could limit your rights later.
What We Can Do
Apex Roofing & General Contractors can inspect your roof, document damage thoroughly with photos and reports, meet with your adjuster on-site to point out findings, and help you understand your policy’s coverage and deadlines. We can also complete the approved San Antonio roof repair or replacement work once your claim is settled.
What We Cannot Do
Under Texas Insurance Code, a contractor is not legally permitted to act as your public insurance adjuster while also performing the repair work. This means we cannot negotiate your settlement on your behalf, sign insurance documents as your representative, or guarantee a specific claim outcome. Be cautious of any contractor who offers to “handle everything” with your insurance company, as that arrangement isn’t legally permissible in Texas and can sometimes limit your ability to dispute a settlement later.
If you need someone to formally represent your interests in a dispute, a licensed public adjuster is the appropriate resource, separate from the contractor completing the repair work.
Why Choose Apex Roofing & General Contractors in San Antonio
- Licensed and Insured: Fully licensed, bonded, and insured for both residential and commercial roofing work across San Antonio.
- Thorough Damage Documentation: We use drone imaging and detailed photo reports to capture the full extent of hail, wind, and storm damage, including what adjusters may miss.
- Deep Knowledge of Texas Insurance Rules: We understand how deductibles, ACV versus RCV policies, and Texas-specific claim deadlines affect your settlement.
- Support for Underpaid or Denied Claims: We help reinspect and re-document damage when a claim doesn’t reflect the actual scope of repair needed.
- Residential and Commercial Experience: From single-family homes to apartment and commercial properties, we understand how claims differ across property types.
- Repair and Replacement Follow-Through: Once your claim is approved, we complete the repair or replacement using manufacturer-compliant materials and methods.
- Recognized Craftsmanship: Our work has earned industry recognition and awards for quality and customer satisfaction across San Antonio.
The Roof Insurance Claim Process in Texas: Our 7 Steps in San Antonio
Filing and managing a roof insurance claim involves several steps, and having an experienced team guide you through each one helps make sure nothing gets overlooked or underpaid.
- Free 37-point damage inspection: our San Antonio roof inspection team evaluates every slope and penetration, documenting storm-related damage with dated photos and drone imaging.
- Written documentation: a report with the full scope of damage, hail-size reference from the NWS storm report, and a repair-or-replace recommendation.
- Decide whether to file: we compare the likely cost to your deductible with you – the Hail Damage Claim Checker does the first pass – and if it isn’t worth a claim, we say so.
- You file; the clock starts: the carrier has 15 days to acknowledge and assign an adjuster, and 15 business days after receiving your documentation to decide.
- Adjuster meeting on site: whenever possible we walk the roof with your adjuster and point out what our report found.
- Scope review and supplements: when the adjuster’s estimate comes back, we compare it line by line against our findings. First scopes routinely leave out decking replacement, drip edge, starter strip, ice-and-water at valleys, ventilation, and the code items San Antonio requires on a re-roof; if your policy carries ordinance-or-law coverage, those belong in the claim, not on your invoice. We document each missing item for a supplement request. Claim help costs you nothing extra – it is included when Apex does the repair or replacement.
- Repair or replacement once approved: the storm damage repair or roof replacement in San Antonio is completed to the approved scope with manufacturer-compliant materials; any withheld depreciation on an RCV policy is released to you after completion.
Throughout, our goal is simple: your claim reflects the true extent of the damage, and every decision stays yours.
Proudly Serving San Antonio TX & Surrounding Communities with Professional Roof Insurance Claims Assistance
Apex Roofing & General Contractors proudly provides roof insurance claims assistance to homeowners and businesses throughout San Antonio, Bexar County, and the surrounding Hill Country communities – including the Northwest Side, Stone Oak, and Alamo Ranch neighborhoods that have taken the heaviest hail in recent seasons. No matter where storm damage strikes, our team brings the same thorough documentation and honest support to every claim, residential or commercial.
Our roof insurance claims assistance extends to San Antonio, Helotes, Leon Valley, Alamo Heights, Shavano Park, Terrell Hills, Boerne, Bulverde, Fair Oaks Ranch, New Braunfels, Seguin, and San Marcos. For a full view of our coverage, visit our service area page.
Get Help With Your Roof Insurance Claim in San Antonio TX Today
Navigating a roof insurance claim alone can mean settling for less than what your damage actually warrants. Apex Roofing & General Contractors provides thorough documentation, on-site adjuster support, and honest guidance so your claim reflects the true scope of the repair. Don’t leave money on the table when a stronger claim is within reach.
Call (726) 727-7663 for a free 37-point roof inspection, or request online and our team will schedule a visit before you file.
Our Company Office & Hours
San Antonio, TX
Apex Roofing & General Contractors
8131 W Hausman Rd Ste 103, San Antonio, TX 78249
Monday: 8AM – 8PM
Tuesday: 8AM – 8PM
Wednesday: 8AM – 8PM
Thursday: 8AM – 8PM
Friday: 8AM – 8PM
Saturday: 8AM – 8PM
Sunday: Closed
Read Our Reviews on Google

Frequently Asked Questions
How long do I have to file a roof insurance claim in San Antonio, Texas?
Most Texas policies require you to report roof damage within one year from the date of loss, though some insurers ask for notice sooner. It’s best to report damage as soon as you discover it rather than waiting.
Will filing a roof claim cause my insurance rates to go up?
Weather-related claims, such as those from hail or wind, typically don’t raise your rates the way an at-fault claim might. However, rate impacts can vary by insurer, so it’s worth reviewing your specific policy.
What's the difference between ACV and RCV on my roof policy?
ACV (Actual Cash Value) factors in depreciation based on your roof’s age, resulting in a lower payout for older roofs. RCV (Replacement Cost Value) covers the full cost to repair or replace your roof without deducting for depreciation.
Can I get a second opinion if I disagree with my adjuster's assessment?
Yes. You have the right to request a reinspection if you believe the adjuster’s findings don’t reflect the actual damage. Apex Roofing & General Contractors can provide documentation to support that request.
What happens if my roof claim is denied?
If your claim is denied, you can request a written explanation, ask for a reinspection, or file a complaint with the Texas Department of Insurance if you believe the denial wasn’t justified.
Can a roofing contractor negotiate my insurance settlement for me?
No. Under Texas law, a contractor cannot legally act as your insurance representative while also performing repair work. A licensed public adjuster is the appropriate resource for that role.
What kind of damage typically qualifies for a roof insurance claim in San Antonio?
Sudden, storm-related damage from hail, wind, or falling debris is typically covered. Gradual wear and tear or lack of maintenance usually isn’t covered under most policies.
How is a supplement different from the original insurance claim?
A supplement is an additional request made after the initial claim if further damage is found or costs weren’t fully accounted for in the original estimate. It’s common when hidden damage is discovered during the repair process.
Does my roof's age affect how much my insurance claim pays out?
Yes, particularly under an ACV policy, where older roofs receive a lower payout due to depreciation. Under an RCV policy, age has less immediate impact, though recoverable depreciation may still apply.
Do I need a professional inspection before I file a claim?
Yes, a professional inspection catches damage that is easy to miss from the ground, such as granule loss or lifted flashing, which strengthens your claim before an adjuster ever visits.
What if my approved claim does not cover the full cost of repair?
Apex Roofing & General Contractors offers financing options to help cover the difference between your approved claim amount and the full repair or replacement cost.
What should I not say to a roof insurance adjuster?
Don’t guess at dates, causes, or the roof’s age – say “I’ll check” and pull the storm date from the NWS storm report and the roof’s install date from your records. Don’t describe the damage as “old,” “minor,” or “probably wear” – those are coverage terms, and the adjuster will write them down. Don’t say you’ve already had it repaired, and don’t sign anything at the meeting. Do walk the roof with your contractor’s report in hand and let the photos do the talking.
How long does a roof insurance claim take in Texas?
A typical San Antonio hail claim runs six to eight weeks from storm to finished roof: week 1, inspection and filing; week 2, the adjuster meeting; weeks 3–4, the scope arrives and any supplement goes in; weeks 4–6, supplement approval and material ordering; weeks 6–8, installation and release of withheld depreciation. In peak hail season (April–June) carrier volume can stretch that to 10–12 weeks. The law sets the carrier’s clock: acknowledge within 15 days, decide within 15 business days of receiving your documentation, pay within 5 business days of accepting. Good documentation on day one is what keeps you at the short end.
Do I have to use my insurance company's preferred roofer?
No. In Texas you choose the contractor. A carrier can suggest a “preferred vendor,” and some, like USAA and State Farm, run programs for it, but you are not required to use one, and the claim payout does not change based on who does the work. Choose a local, insured roofer who documents the roof and will still be here at renewal time – see how to vet a San Antonio roofer.
Can a roofer waive or pay my deductible in Texas?
No. Since 2019, Texas law (House Bill 2102, now Business & Commerce Code §27.02) makes it a Class B misdemeanor for a contractor to waive, rebate, or absorb an insurance deductible, and since 2023 insurers can require proof you paid it before releasing the final payment. A roofer who offers to “take care of the deductible” is offering to commit a crime on your behalf, and the same roofer usually inflates the scope to cover it. Apex does not waive deductibles; we do help you plan for it with financing.
Testimonials
What they’re saying about us